 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528


20/10/2026
Accepting P-cards online takes no special account, but the data you send sets your fees. Learn Level 2 and 3 data, PCI duties and checkout setup.
19/10/2026
Where HIPAA applies to telemedicine card payments, when you need a BAA, how PCI DSS fits in, and what to check before choosing a merchant account.
18/10/2026
Where credit card surcharging is allowed, capped or banned in 2026, how Visa's rules stack on top, and how dual pricing and cash discounts differ.
15/10/2026
Prepare a debt collection agency merchant account application with licenses, creditor contracts, bank records, and PCI and NACHA evidence underwriters review.
14/10/2026
Build POS API integrations with OAuth, REST endpoints, SPIs, webhooks, and reconciliation patterns, with practical checks for SaaS and high risk merchants.
13/10/2026
Compare cloud and traditional POS costs, offline reliability, and PCI security questions, with checks for merchants handling high risk payments.
12/10/2026
Prepare to bill DoD and large B2B customers with five essentials, from GSA SmartPay and WAWF compliance to export screening and merchant underwriting.

11/10/2026
See how U.S. consumers dispute ACH debits, when Regulation E caps liability, and how merchants use NACHA rules and records to contest returns.
8/10/2026
Operations-first guide to Visa chargeback rules for merchants. Meet the 31 day VCR timeline, map evidence to reason codes, and use an eight item readiness...
7/10/2026
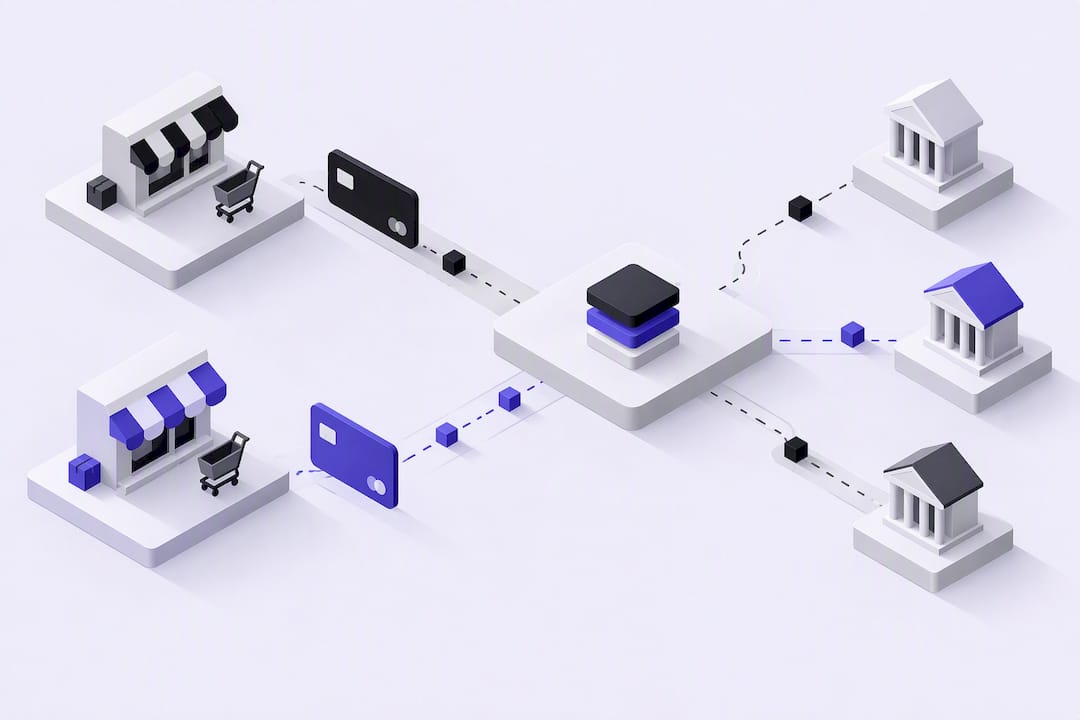
Technical, operator‑focused guide to marketplace split payments: architecture models, API patterns, KYC, reserves, 1099‑K and FinCEN risks, plus CARDZ3N...
6/10/2026
SMBs & freelancers: accept online invoice payments fast and secure. 5-step setup and when to call a payments specialist.
5/10/2026
Playbook for merchants and payment teams. Meet Visa's 30 day pre arbitration window, build CE3.0 evidence that validates in VROL.
4/10/2026
Practical, dollar-first steps for merchants to cut the $128 average all-in chargeback cost. Learn prevention, quick responses, and when to automate or...
8/10/2026
See how credit card processing works from tap to payout: authorization, clearing, settlement and the fees at each stage, plus what small businesses should compare when choosing a provider.
7/10/2026
ACH return code R16 means the receiving account is frozen. Learn why R16 happens, how long you have to act, and how to handle the payment and the customer.
6/10/2026
Level 3 data processing sends line-item detail with a card payment so eligible commercial and government cards can qualify for lower interchange. Learn how it works and who benefits.
3/10/2026
What does issuer decline mean? Learn why a card issuer declined a payment, what an issuer declined message tells you, and how merchants can reduce declines on debit and credit cards.
4/10/2026
EIN vs tax ID vs TIN explained for merchant account applications. Learn whether an EIN is the same as a tax ID and what to enter on your processing application.
3/10/2026
What is an ACH credit? Learn the ACH credit meaning, how it differs from an ACH debit, and what an ACH credit means on your bank statement.
3/10/2026
ACH vs wire transfer: compare speed, cost, reversibility and best uses. See the difference between ACH and wire transfers and when each payment method fits your business.
2/10/2026
3D Secure 2.0 adds a data-rich authentication step to online card payments. Learn how the 3DS2 flow works, what frictionless and challenge flows are, and when merchants should use it.
2/10/2026
Card testing is when fraudsters run small transactions to find out which stolen card numbers work. Learn the warning signs, how card testing hurts merchants, and the tools that stop it.
2/10/2026
FluidPay is a payment gateway and processing platform used by merchants and payment partners. Learn what to evaluate when comparing FluidPay with other gateways, including fees, integrations and risk fit.
2/10/2026
The NMI payment gateway connects your website, app or terminal to the card networks. Learn what NMI is, how a payment gateway works, and what to ask before choosing a gateway for your business.
2/10/2026
Friendly fraud happens when a cardholder disputes a legitimate purchase. Learn the common causes, how it differs from true fraud, and how merchants can prevent and fight friendly fraud chargebacks.
2/10/2026
ACH SEC codes, also called Standard Entry Class codes, tell the bank network what type of authorization sits behind an ACH payment. Learn what PPD, CCD, WEB and TEL mean and which SEC code to use.
5/10/2026
An AVS address mismatch happens when the billing address a customer entered does not match what the card issuer has on file. Learn what AVS mismatch codes mean, why they happen, and how to reduce false declines without raising fraud risk.
4/10/2026
Implementation first interchange optimization for B2B and high risk merchants. Learn Visa IDX and gateway API integrations, reconciliation practices, and...
3/10/2026
Implementation-first 3DS2 guide for payments engineers and ops: SDKs, timeout handling, selective triggers for high risk merchants, and steps to secure...

1/10/2026
What to look for in a merchant services partner program, and how merchant services residual income is usually structured.
3/10/2026
How long does an ACH transfer take, and how long do ACH transfers take around holidays? Learn FedACH same-day windows, bank cutoffs and practical fixes to avoid missed ACH deadlines.
3/10/2026
Technical guide for ISVs and product owners: choose the right integration model, limit PCI scope, manage underwriting for high risk merchants, and launch...
3/10/2026
Learn when to void or refund, how Visa’s 24-hour reversal window changes the choice, and the steps merchants should take to avoid holds, fees, and...
3/10/2026
Decline dynamic currency conversion in most cases. See how Visa and Mastercard disclosure rules protect you, how to read terminal rates, and when to...
3/10/2026
A compliance-safe playbook for high-risk merchants: preserve termination evidence in the first 72 hours, compile an underwriter-ready file, and pursue...
3/10/2026
SMBs: Learn why underwriting, sponsor banks, and PCI/FFIEC risk determine payment access and what to check when choosing gateway and processor partners.
3/10/2026
Developers: implement hosted payment pages, handle session redirects and webhooks, reduce PCI scope to SAQ-A, and onboard high risk accounts.
3/10/2026
Check 21 processing for treasury teams: Regulation CC, Fed and X9 file rules explained, plus capture, returns, reconversion, and reconciliation steps.
3/10/2026
Implementation-focused help for payments teams: pick network or merchant tokens, migrate stored PANs safely, and cut subscription churn.
3/10/2026
Complete R01–R85 ACH return codes reference, including the R16 return code, with step-by-step remediation workflows for US finance teams plus high-risk merchant controls.
3/10/2026
Engineering-first guide for merchants: map each velocity check to the fraud it stops, deploy counters and TTLs for real time screening, and tune...
3/10/2026
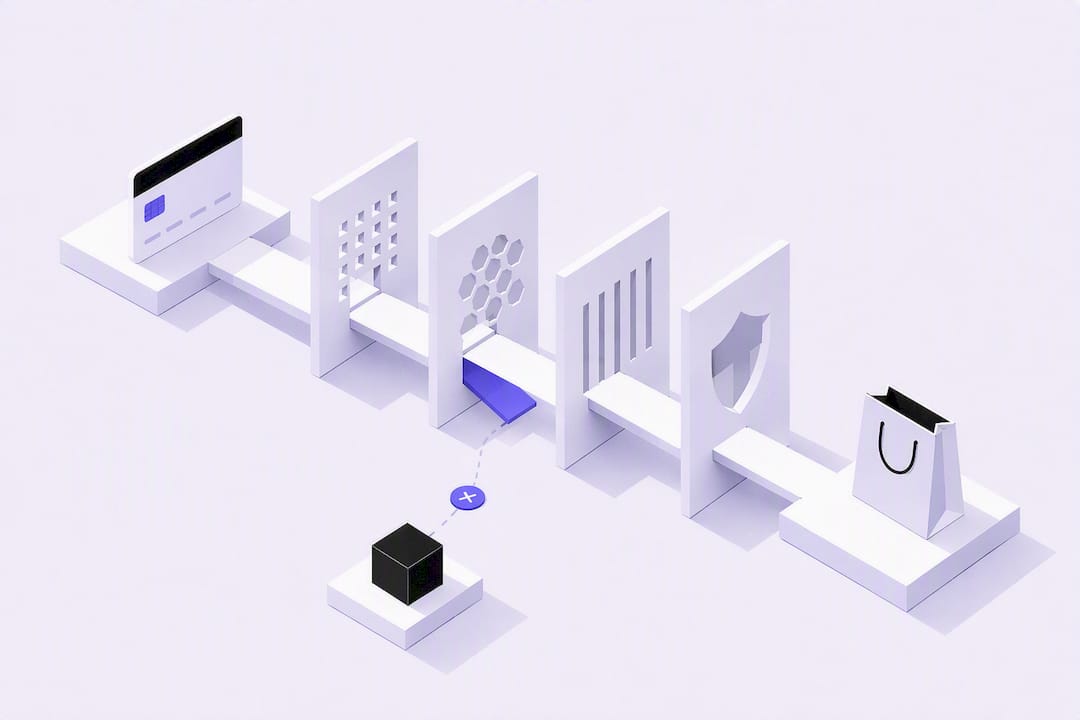
Merchant focused steps to cut card not present fraud without wrecking checkout: block card testing, use risk based 3DS, tokenize stored cards, and monitor...
3/10/2026
For SaaS platforms and ISVs: when instant onboarding and embedded payouts beat negotiated ISO rates, and why $500,000/year often tips the choice.
3/10/2026
Stripe's president of technology says checkout is dying. It isn't — it's moving from a front-end page to backend, API-driven payment infrastructure.
3/10/2026
For merchants: match exact evidence to each reason code and use expected value math to decide which chargebacks to contest.
3/10/2026
What is an electronic check, and how does eCheck work? An electronic check payment is an ACH debit from a customer's bank account. Compare eCheck vs ACH for landlords and B2B: clearing time, costs, authorization and returns.
3/10/2026
PCI-aware setup for merchants to launch virtual terminal payments and meet SAQ C-VT. Enable AVS/CVV, set user roles, and go live in a day.
3/10/2026
Find when interchange plus lowers your costs. Worked examples, a procurement checklist, and CARDZ3N's high risk guidance to calculate break even.
3/10/2026
Practitioner focused breakdown of PCI DSS 4.0 changes with a prioritized remediation checklist to meet March 31, 2025 and CARDZ3N tips.
3/10/2026
How merchants use Ethoca Alerts: integrate portal or API, fix billing descriptors, and act within the 24 hour window using CARDZ3N workflows.
3/10/2026
Chargeback protection starts with prevention. Apply five practical steps for chargeback fraud prevention: billing descriptors, 3D Secure, aligned capture, receipts and clear renewals, with reason-code guidance.
3/10/2026
Actionable prevention playbook for merchants to stop friendly fraud chargebacks using CE3.0 evidence, Order Insight, and CARDZ3N case tactics.
3/10/2026
Audit ready PCI checklist for high risk and B2B merchants. Scope the CDE, collect audit evidence, and meet PCI DSS v4.0.1 requirements.
3/10/2026
Practical B2B ACH payment processing guide: 1–3 day timing and Same Day ACH, pricing drivers, SEC code authorization, and controls to reduce returns and...
3/10/2026
Run a three month forensic workflow that uses AI as a fast first pass and human verification to locate and recover hidden card processing fees.
4/10/2026
What is a contactless payment? Learn how tap-to-pay and NFC work, whether it's secure, and how to accept it at your business.
11/9/2026
Cut subscription chargebacks below 1% with a 12-point tactical guide covering 3DS, RDR, CDRN, Compelling Evidence 3.0, and VAMP 2026 thresholds.
11/9/2026
Visa's VAMP threshold dropped from 2.2% to 1.5% on April 1, 2026. Learn the new fees, formula, and 12-step compliance checklist for high-risk merchants.
11/9/2026
Understand how payment processing works, compare providers, and choose the right company and payment methods to lower fees, reduce risk, and boost your approvals.
11/9/2026
Learn what to research when choosing a credit card processing company, from fees and contracts to support and security, so you avoid costly mistakes.
11/9/2026
Discover online payroll services that calculate, file, and pay taxes for you, save time with auto payroll, and give you control of cash flow and compliance.
7/9/2026
Discover what a merchant service account is, how it lets your business accept credit, debit, and ACH payments, and key steps to choose the right provider.
2/10/2026
How to set up a merchant account in six practical steps: choose a provider, compare fees, apply, pass underwriting, and get approved so you can start accepting credit and debit card payments.
7/9/2026
Understand the pros and cons of aggregate vs direct merchant accounts, including risk, control, and approvals, so you choose the best setup for your business.
The CARDZ3N blog covers the practical side of accepting payments: how merchant accounts are underwritten, what drives processing fees, how to keep chargebacks under control, and how gateways, POS systems and ACH fit together. Articles are written for business owners, finance teams and developers who want clear answers instead of sales talk.
Each category groups related guides, company news and industry updates so you can go deeper on one topic at a time. If a question about your own setup is not answered here, our payments specialists can review your statements, contract and risk profile and recommend next steps for your business in the USA, Canada, the UK or the EU.
CARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.