 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528


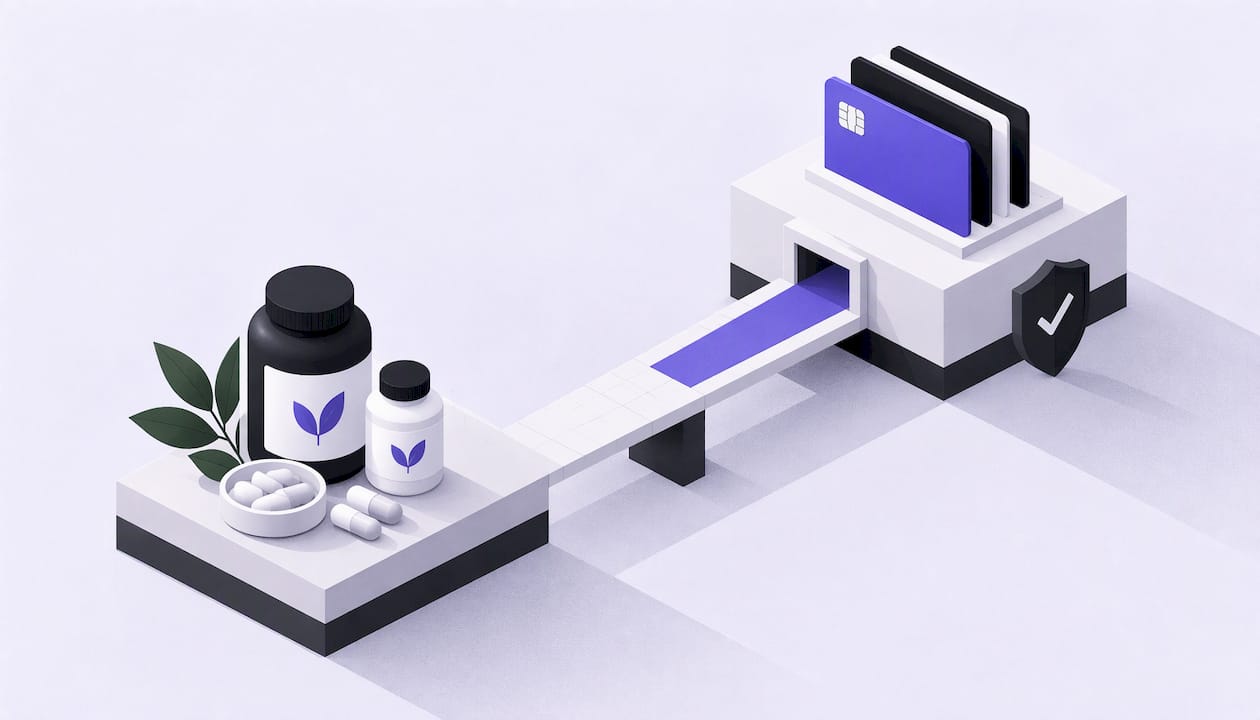


Nutraceutical payments work reliably when the account is built for your category from the start: a high-risk merchant account placed with a sponsor bank that underwrites supplements, with your claims, refund terms and chargeback controls documented before you apply. Aggregators such as Stripe, PayPal and Square are quick to set up, but they can freeze or terminate supplement accounts after launch. A specialist account is the stable alternative. At CARDZ3N we place nutraceutical and supplement merchants through our supplement merchant account program, with hands-on underwriting support and reserve and pricing terms stated up front.
This guide covers what a nutraceutical merchant account is, why underwriters treat the category as high risk, what to put in your application, how fees and reserves work, and how to keep your chargeback ratio low enough to stay approved.
A merchant account is the arrangement that lets your business accept card payments. A sponsor bank (the bank that holds the account relationship with the card networks) underwrites you, a processor moves the money, and a gateway captures the card details at checkout. “Nutra merchant account” and “supplement merchant account” mean the same thing: an account approved by a bank that knowingly accepts your product category.
That last point matters. Aggregators pool thousands of small merchants under one master account and approve you in minutes with little review. Their speed is also their weakness: your product is reviewed after you start selling, often by an automated flag. A dedicated merchant account is underwritten up front, so the bank has already agreed to your products, your marketing claims and your expected volume.
For a nutraceutical brand, a complete payments setup usually has these parts:
The classification is about how the category behaves in payments and how it is regulated, not about the quality of your products. Underwriters generally look at four things.
Under the Dietary Supplement Health and Education Act of 1994 (DSHEA), supplement labels may carry structure/function claims, such as “calcium builds strong bones,” without FDA pre-approval. The manufacturer must have substantiation that the claim is truthful and not misleading, and the label needs the standard disclaimer, according to the FDA’s structure/function claims page. Because nothing is approved in advance, a bank cannot take a regulator’s sign-off as proof that your marketing is compliant. It looks at your claims itself.

Supplements are often sold on free-trial, auto-ship or continuity plans. A customer who forgets a recurring charge may call the card issuer instead of you, and that becomes a chargeback. Disputes are the number one reason processors review or close supplement accounts.
Most nutraceutical sales happen online, where the card is not physically present. Fraud liability on those transactions falls largely on the merchant.
Visa and Mastercard track merchant fraud and dispute ratios, and the thresholds have tightened in recent years. A merchant that crosses them can face fees, remediation requirements or loss of processing. Bank underwriters price this exposure into reserves and approval decisions, so a supplement merchant with a clean, documented dispute process looks much better on paper.
Underwriters read your website. If the copy suggests a product treats or cures a disease, expect a decline or a termination, whichever processor you use. Three official rules shape what a clean site looks like.
The practical rule: before you apply, audit your product pages, ads, emails and influencer content for disease language, and make sure your claim substantiation file is ready to hand to an underwriter. A merchant whose site, label and notification all agree is easier to approve.
A complete application shortens underwriting. Gather these items first.
| Item | What the underwriter wants to see |
|---|---|
| Business documents | Formation papers, EIN, ownership details, business bank account |
| Processing history | Recent statements from any prior processor, including chargeback and refund ratios |
| Product information | Full product list, ingredients, labels, supplier or contract manufacturer details |
| Claims support | Substantiation for structure/function claims and your FDA notification records |
| Website | Live or staging site with pricing, shipping, refund and cancellation terms, privacy policy, contact details |
| Billing model | One-time, subscription, trial or continuity offers, with cancellation steps |
| Volume expectations | Monthly volume, average ticket, expected peak months |
If you were shut down by an aggregator, include the termination notice and a short explanation of what caused it, whether that was a dispute spike, a claims flag or a volume jump. New businesses with no processing history should add supplier invoices, a launch plan and projected volume so underwriters can judge the model.
High-risk pricing is quote-based, because it depends on your products, ticket size, billing model and history. At CARDZ3N, pricing is quote-based and reserve structures are laid out transparently, not left vague. These are the terms to understand in any agreement:
Compare quotes line by line, including the reserve. A low headline rate with a large, long-held reserve can cost you more in working capital than a slightly higher rate with clear release terms. If cash flow is tight while the reserve builds, business lending and working capital is part of what we offer.
When you evaluate providers, weigh these against your actual business.
| Criterion | Why it matters for supplements |
|---|---|
| Category acceptance | The sponsor bank must approve supplements in writing, not tolerate them until a flag appears |
| Multi-bank access | A second routing option protects you if one bank changes its appetite |
| Underwriting support | Someone who helps you present claims, billing terms and history correctly |
| Reserve clarity | Percentage, duration and release schedule stated before you sign |
| Recurring billing | Support for subscriptions, trials and decline recovery |
| Chargeback tools | Prevention, alerts and dispute representment in one place |
| Gateway flexibility | Integrations with your cart or subscription platform |
| Geographic reach | U.S. processing now, with Canada, UK or EU accounts if you expand |
On these points, we built CARDZ3N as a specialist for merchants that generic processors turn away: hands-on underwriting support, multi-bank and multi-rail approval resilience, and transparent reserve and pricing terms, backed by top-tier sponsor banks.
Cards are the core, but a supplement brand benefits from a wider mix.
Integration matters as much as acceptance. Confirm your cart, subscription tool and gateway work together before launch, since moving gateways mid-stream disrupts stored cards and recurring schedules.
For a nutraceutical merchant, the chargeback ratio is the metric that decides whether an account lasts. Visa’s VAMP program combines fraud and dispute activity into a single monthly ratio against settled transactions, and the Excessive threshold for merchants has been tightened. Check Visa’s current published thresholds and minimum counts, since they change and your acquiring bank may apply stricter internal limits.
Most supplement disputes come from a few predictable sources:
| Dispute source | Typical trigger | Prevention tactic |
|---|---|---|
| Unrecognized charge | Billing descriptor does not match your brand | Use a clear descriptor and include your support number |
| Forgotten subscription | Customer did not expect a recurring charge | Disclose terms at checkout, send renewal reminders, make cancellation easy |
| Trial conversion | Free trial rolls into a paid plan | Show the trial end date and price in a confirmation email |
| Item not received | Shipping delay or lost package | Send tracking and delivery confirmation |
| Product dissatisfaction | Customer expected different results | Offer a simple, visible refund policy and answer support quickly |
| True fraud | Stolen card used at checkout | Use address verification, CVV checks and 3D Secure |
Three practices work together. First, stop disputes before they post with clear descriptors, order confirmations and fast refunds. Second, screen fraud at checkout with AVS, CVV and 3D Secure, the extra cardholder authentication step that shifts liability on authenticated transactions. Third, contest the disputes that remain with organized evidence: order records, proof of delivery, terms accepted and customer communication. ChargebackZ3N and our chargeback management service cover prevention, monitoring and dispute representment, and our guide to preventing chargebacks goes deeper on tactics.
Most supplement merchants come to us after a freeze. The pattern is nearly always the same: an aggregator approved the account in minutes, volume grew, a handful of disputes or a flagged claim triggered a review, and the funds were held with little explanation. The product was rarely the problem. The account type was.
We built CARDZ3N around the opposite sequence. Underwriting comes first, with your claims, billing model and processing history reviewed by people who understand the category, so the bank that approves you has already accepted what you sell. Our model combines top-tier sponsor banks with multi-bank and multi-rail resilience, so a single bank’s policy shift does not have to stop your sales.
We also think reserve and pricing terms should be readable before you sign. Our pricing is quote-based because it reflects your actual risk profile, and we state the reserve structure openly. For a growing supplement brand, predictable terms are what let you plan inventory, ad spend and payroll.
The brands that stay approved the longest treat payments as part of operations: clean claims, clear subscription disclosures and a chargeback process that runs every week, not only when a notice arrives.
Joshua Benedetti
If your supplement or nutraceutical business has been declined, frozen or closed by a mainstream processor, or you are launching and want an account that fits from day one, start with our high-risk merchant account page or go straight to the nutraceutical and supplement merchant account program. We handle underwriting and merchant account placement, gateway integrations, recurring billing, ACH and eCheck, and chargeback prevention. If you sell in other markets, we also offer UK nutraceutical payment processing and Canadian nutraceutical payment processing.
Planning the sequence avoids launch delays.
Volume jumps are a quiet cause of account reviews. A merchant that tells its processor about a planned campaign is treated differently from one whose daily volume triples without notice.
Most processors place supplement and nutraceutical merchants in the high-risk tier. The reasons are category-level: claims are not pre-approved by regulators, subscription billing is common, and sales are mostly card-not-present. A merchant with clean claims, clear billing terms and a low dispute ratio can secure strong terms inside that tier.
Payment providers use the terms interchangeably. Underwriters care about what your products are, what you claim for them and how you bill, not which label you use. Supplements marketed under DSHEA, with compliant structure/function claims, are the standard case.
Timing depends on how complete your application is and how quickly the bank’s underwriting questions are answered. Having claims support, site policies and processing statements ready at submission is the best way to shorten it. We can tell you what applies to your file after reviewing it.
Yes. A prior termination does not rule out approval. Include the termination notice, explain the cause and show what you changed, such as clearer disclosures or tighter dispute handling. Specialist underwriting is built for these cases.
If you sell wholesale or to practitioners, ACH and eCheck are worth having since they handle larger invoices at lower per-transaction cost than cards. Consumer-only brands can start with cards and add ACH later.
Every merchant's processing setup is different, so the right answer depends on your industry, sales channels, average ticket size and chargeback history. CARDZ3N's payments specialists review those details with you and match your business with the right sponsor bank, gateway and risk tools, whether you sell online, in store, by invoice or on a recurring subscription.
We work with merchants across the USA, Canada, the UK and the EU, including high-risk, B2B and fast-growing businesses that traditional processors often turn away. If you would like a second opinion on your current rates, contract terms or approval options, contact our team for a free, no-obligation processing review.
Joshua Benedetti is the CEO of CARDZ3N, a Las Vegas-based merchant services provider specializing in high-risk payment processing and B2B payment technology.
Joshua Benedetti on LinkedInCARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.