 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528


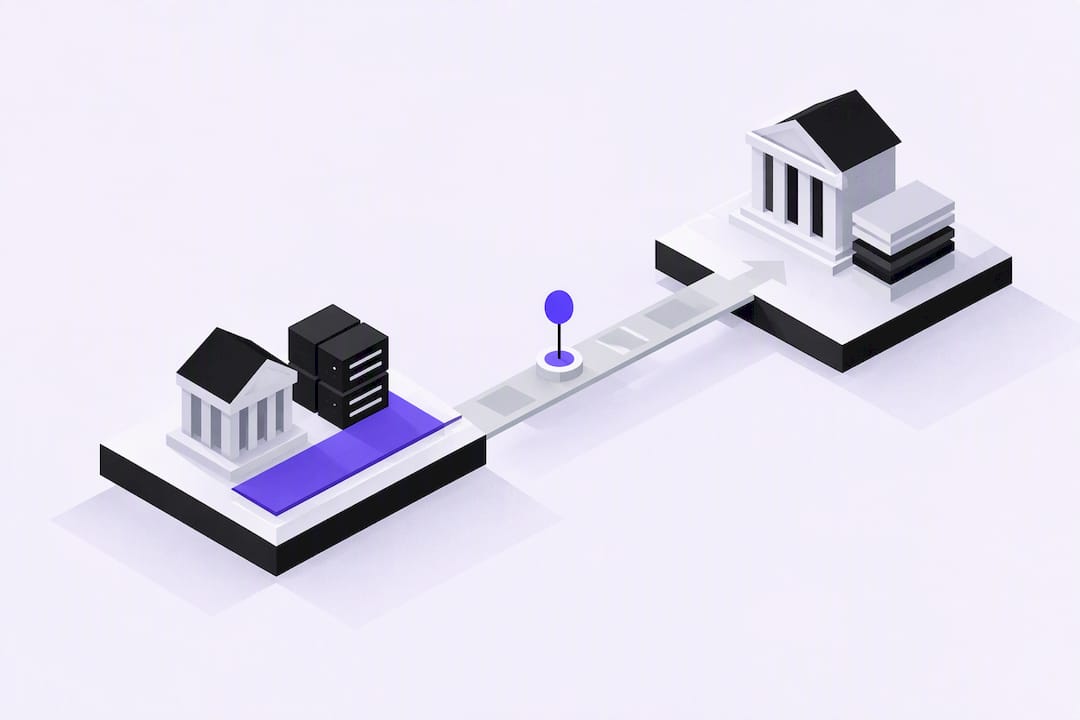
Credit card processing looks instant at the counter, but several parties are involved behind the scenes. Knowing the steps makes it easier to compare providers and to understand your statement.
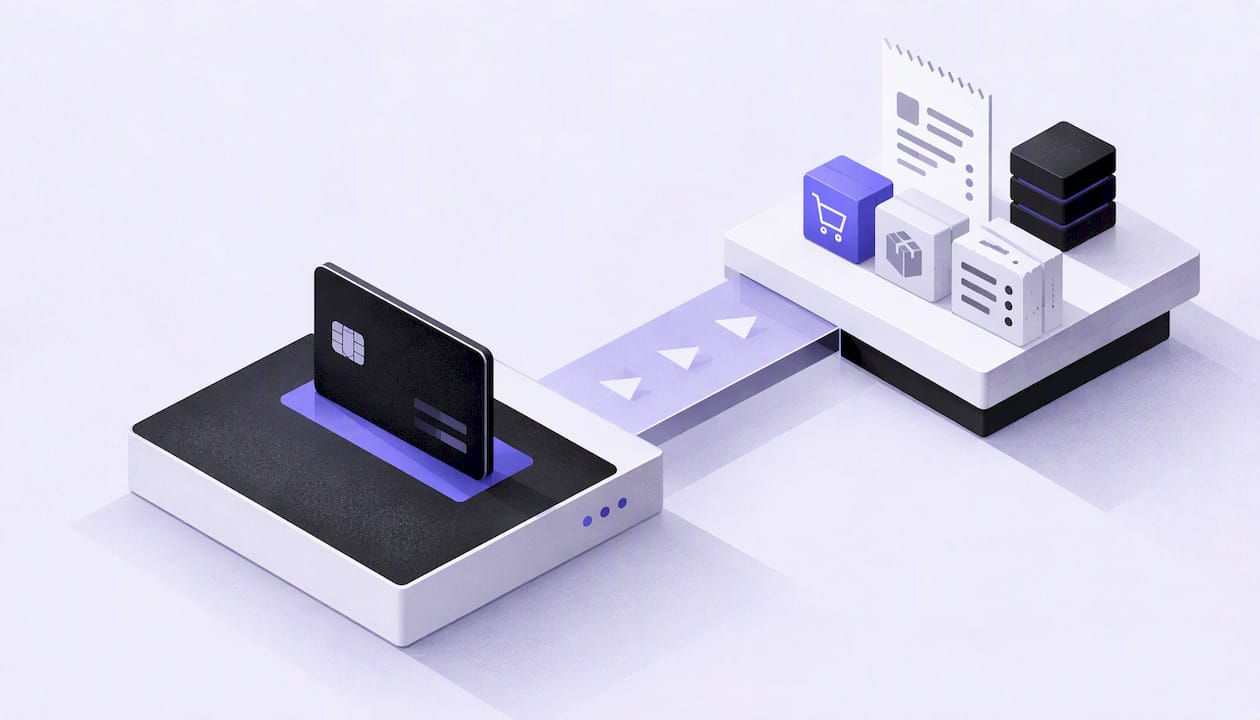
The customer taps, inserts or enters a card. The gateway sends the request through the processor and network to the issuer, which checks funds and fraud signals and replies with an approval or a decline. This usually takes seconds. If a decline occurs, our post on issuer declines explains what to do.
At the end of the day the merchant submits a batch of approved transactions. The processor sends them to the networks, which tell each issuer how much it owes.
The issuer sends funds to the acquirer, which deposits them into your bank account, minus fees. Funding speed depends on your provider and account type; high risk accounts may have a reserve.
Each sale carries interchange (to the issuer), network assessments and processor markup. Pricing can be interchange-plus, flat rate or tiered; learn more in interchange-plus pricing and our fees explained page.
Compare total cost, contract terms, funding speed, support and the tools you get, such as a payment gateway, POS and chargeback management. Start with our merchant services overview or read the full credit card processing guide.
Every merchant's processing setup is different, so the right answer depends on your industry, sales channels, average ticket size and chargeback history. CARDZ3N's payments specialists review those details with you and match your business with the right sponsor bank, gateway and risk tools, whether you sell online, in store, by invoice or on a recurring subscription.
We work with merchants across the USA, Canada, the UK and the EU, including high-risk, B2B and fast-growing businesses that traditional processors often turn away. If you would like a second opinion on your current rates, contract terms or approval options, contact our team for a free, no-obligation processing review.
Joshua Benedetti is the CEO of CARDZ3N, a Las Vegas-based merchant services provider specializing in high-risk payment processing and B2B payment technology.
Joshua Benedetti on LinkedInCARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.