 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528


Interchange rates are the fees a merchant's bank pays the cardholder's bank every time a card payment is processed. They are usually the largest part of what a business pays to accept cards, and they are set by the card networks rather than by your processor. Understanding how interchange works is the first step to reading your statement and lowering your costs.
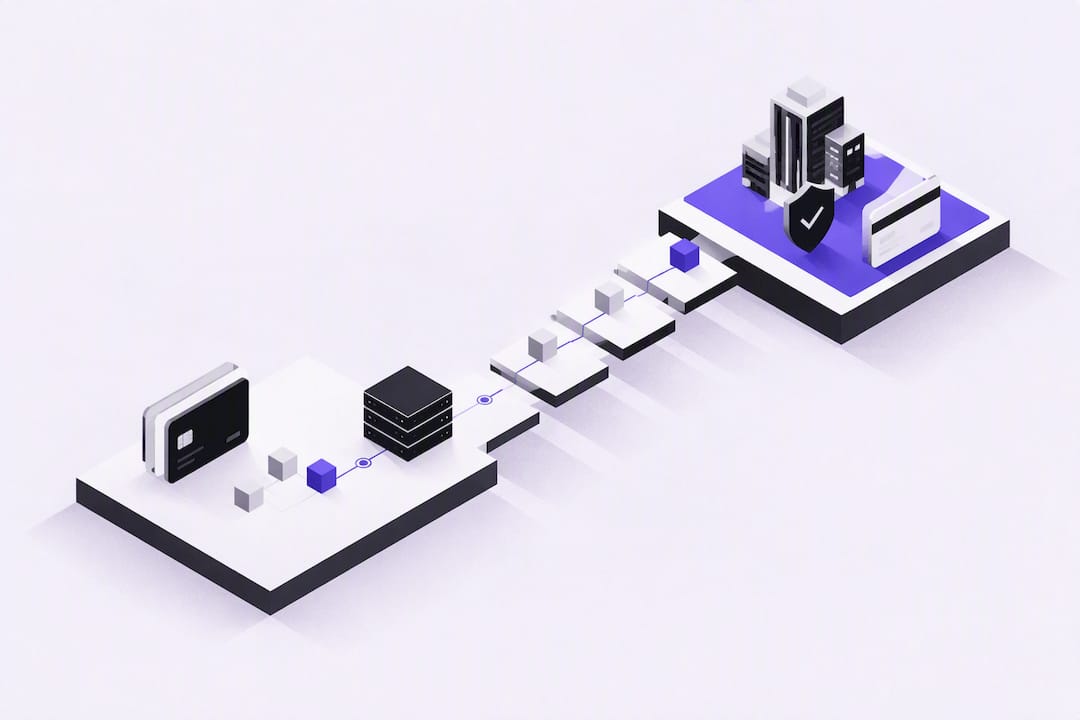
Interchange is a fee paid by the acquiring bank (your merchant account provider's bank) to the issuing bank (the bank that issued the customer's card). Visa, Mastercard, Discover and American Express publish interchange schedules, and they update them on a regular cycle, commonly in April and October. The issuing bank uses interchange to help cover the cost of fraud, credit risk, cardholder rewards and running the card program. The merchant ultimately bears the cost, because it is passed through in the price of processing.
A processing statement usually combines three layers:
Interchange and assessments are the same no matter which processor you use. Markup is the part you can negotiate, which is why pricing models matter. Read our guide to interchange-plus pricing to see how markup is shown on a statement.
There is no single interchange rate. Each transaction falls into a category with its own rate, usually a percentage plus a fixed amount. The main factors are:
Networks publish many categories, so rates vary widely. One widely cited industry guide puts typical U.S. Visa and Mastercard interchange at roughly 1.15% to about 2.7% plus a few cents per transaction, with American Express and premium or commercial categories often higher. Treat any range as a guide only, because your own rate depends on your mix of cards and transaction types, and the schedules change.
Your pricing model decides how much of this you can see:
For a plain-English look at where fees show up on a statement, see credit card processing fees explained.
High-risk businesses often pay more overall because of higher markup, reserves and card-not-present volume, even though interchange itself is set by the networks. A processor that works with high-risk merchants can explain which part of your cost is fixed and which part is negotiable. Learn more about high-risk merchant accounts and our reserve and pricing playbook.
The card networks, such as Visa and Mastercard, set interchange schedules. Processors and merchants do not set them.
Not directly. Interchange is the same for every merchant in a category. You can negotiate the processor markup and improve how transactions qualify.
Online and phone payments carry higher fraud risk than in-person chip or tap payments, so they usually fall into higher-cost interchange categories.
No. Your total cost includes interchange, network assessments and your processor's markup, plus any monthly or per-transaction fees on your agreement.
Networks update their schedules on a regular cycle, commonly twice a year. Check with your processor for the changes that affect your account.
Every merchant's processing setup is different, so the right answer depends on your industry, sales channels, average ticket size and chargeback history. CARDZ3N's payments specialists review those details with you and match your business with the right sponsor bank, gateway and risk tools, whether you sell online, in store, by invoice or on a recurring subscription.
We work with merchants across the USA, Canada, the UK and the EU, including high-risk, B2B and fast-growing businesses that traditional processors often turn away. If you would like a second opinion on your current rates, contract terms or approval options, contact our team for a free, no-obligation processing review.
Joshua Benedetti is the CEO of CARDZ3N, a Las Vegas-based merchant services provider specializing in high-risk payment processing and B2B payment technology.
Joshua Benedetti on LinkedInCARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.