 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528




A high-risk MCC is a four-digit merchant category code that card networks tie to elevated fraud, chargeback or regulatory exposure. If your code is on that list, your acquirer needs special registration with the network before it can legally board you, which is why mainstream processors reject or freeze these merchants and why a specialist underwriter is the practical route. At CARDZ3N, we place high-risk merchants with sponsor banks that handle these categories, and this guide shows which codes matter, what 6051, 7994, 5967 and 7273 describe, and what your code changes in underwriting.
An MCC (merchant category code) is a four-digit number describing your primary line of business. Per Visa’s Merchant Data Standards Manual, the code is assigned to describe the merchant’s primary business based on annual sales volume. Acquirers and their agents must assign the correct one, and Visa keeps the right to require corrections.
Two practical points follow:
For a general primer on how codes work beyond the high-risk subset, see our guide to merchant category codes.
Visa’s manual names a set of codes for which every card-absent transaction (online, phone, mail order) falls under its high-integrity-risk rules, plus a second set where only certain card-absent transactions do. The table lists them.
| MCC | Description | Scope under Visa’s list |
|---|---|---|
| 5122 | Drugs, Drug Proprietaries, Druggist Sundries | All card-absent transactions |
| 5912 | Drug Stores, Pharmacies | All card-absent transactions |
| 5966 | Direct Marketing, Outbound Telemarketing | All card-absent transactions |
| 5967 | Adult Content and Services | All card-absent transactions |
| 5993 | Cigar Stores and Stands | All card-absent transactions |
| 7273 | Dating Services | All card-absent transactions |
| 7995 | Betting, including lottery tickets, casino gaming chips, off-track betting and wagers at race tracks | All card-absent transactions |
| 4816 | Computer network and information services | Certain card-absent transactions |
| 5816 | Digital goods, games | Certain card-absent transactions |
| 5968 | Direct marketing, continuity and subscription merchants | Certain card-absent transactions |
| 6211 | Securities brokers and dealers | Certain card-absent transactions |
| 6051 / 6012 | Non-financial institutions and financial institutions (merchandise, services and crypto-related activity) | Certain card-absent transactions |
The source for every row is the Visa Merchant Data Standards Manual (October 2026 edition). Code titles are shortened here, so check the manual for the exact wording and conditions before you rely on one.
Most readers land on this list because of what they sell: pharmacy and telemedicine merchants see 5122 and 5912, adult and dating operators see 5967 and 7273, gaming operators see 7995, and crypto-adjacent businesses see 6051. Vape and tobacco retailers should confirm with their underwriter which code applies to their products, since classification depends on what you sell and how.
MCC 6051 covers non-financial institutions that handle foreign currency, cryptocurrency, money orders, account funding, travelers cheques and debt repayment. It is high risk: Visa’s manual lists 6051 (with 6012) as high integrity risk for card-absent crypto merchants such as exchanges, wallet providers and on-ramp providers, and those transactions must carry Special Condition Code 7 (Visa manual). If you move money for customers, our page on MSB and remittance merchant accounts covers the category.
MCC 7994 is Video Game Arcades/Establishments, and it is Mastercard’s registration category for skill games, so the label comes mainly from Mastercard’s program rather than Visa’s card-absent list (Visa manual). In practice, an arcade selling tokens face to face and an online skill-game operator are underwritten very differently. Describe your model accurately at application: the underwriter sets the final code and the registration that goes with it.
MCC 5967 is Adult Content and Services: subscriptions, video streaming, audio-text and, per the October 2026 Visa manual, escort services. Mastercard still titles 5967 as Direct Marketing, Inbound Telemarketing Merchants in its Quick Reference Booklet, and directs audiotext and videotext providers such as adult chat sites to use it. So the same four digits can read differently by network, yet the underwriting consequence is the same.
MCC 7273 is Dating Services and appears on Visa’s list for all card-absent transactions. Escort services moved out of 7273 into 5967 in Visa’s October 2026 manual edition, so a business that was previously coded under 7273 should confirm its code at its next review.
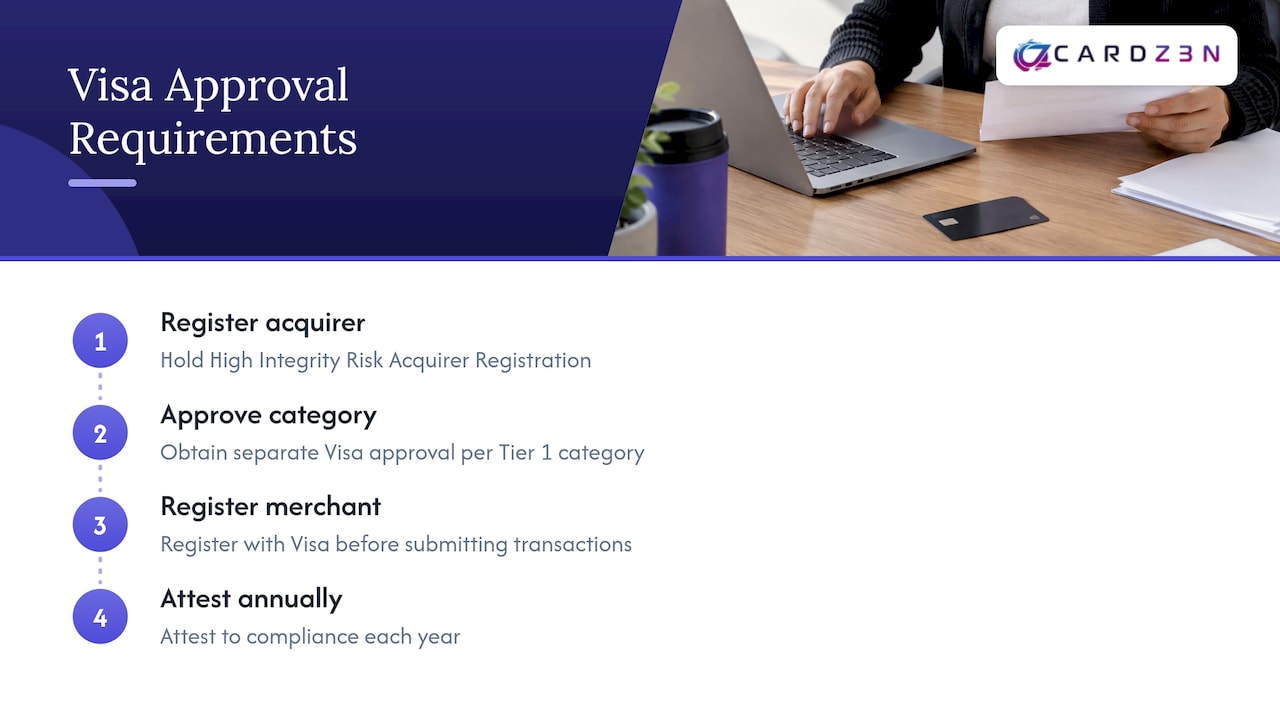
The reason a high-risk MCC narrows your options is structural, not a matter of a processor’s mood. Under Visa’s Integrity Risk Program (a 2023 regional edition), an acquirer must hold High Integrity Risk Acquirer Registration, plus separate Visa approval for each Tier 1 category, before soliciting, contracting with or processing for a merchant in that category. Every such merchant must be registered with Visa before submitting transactions, and compliance is attested to annually.
The program defines Tier 1 as businesses where there is a higher risk of illegal activity occurring without proper controls, with potential harm to individuals’ health, safety or wellbeing. That is why adult content (5967) sits in the same tier as gambling and pharmacies, and why acquirers need approval per category instead of one blanket registration.
Payment facilitators face the same wall. Visa’s Payment Facilitator and Marketplace Risk Guide (April 2021) requires acquirers to obtain a High-Brand Risk Acquirer Registration before contracting with a high-brand-risk merchant. Payment facilitators must register as a High Risk Internet Payment Facilitator before signing such merchants, and marketplaces are prohibited from soliciting them.
This explains the pattern behind most freezes and rejections. A general-purpose processor that is not registered for your category cannot carry you however clean your books look. When its risk team finds your volume under a high-risk code, the account is closed.
You should expect these differences from a standard low-risk merchant account:
On April 1, 2025, Visa launched VAMP (the Visa Acquirer Monitoring Program), which replaced VFMP and VDMP. According to the Merchant Advisory Group’s summary, it monitors card-not-present activity using reported TC40 fraud plus non-fraud disputes, divided by total settled transactions, with thresholds for acquirers and merchants becoming stricter from January 1, 2026. For a high-risk merchant, where baseline dispute rates already run high, the ratio is the number to watch weekly. Our VAMP thresholds guide breaks down the current tiers, and ChargebackZ3N is our chargeback prevention and dispute management service.
Because you do not set your own code, the work is in making sure it matches reality. Mismatches can be costly, and the rules say so.
American Express’s Merchant Regulations (April 2026) require you to give an accurate business description so Amex can assign the MCC and to use the most accurate MCCs in all authorizations and submissions. They also require you to remediate MCC mismatches at your own expense, and they reserve Amex’s right to correct an assignment in its sole discretion without advance notice.
A workable routine:
Misclassification works both ways. Declaring a lower-risk category to avoid scrutiny risks termination when the network or acquirer corrects it. Accurate disclosure to an acquirer registered for your category is what keeps an account stable.
If you were turned away or shut down by a mainstream processor, the code is usually the reason, not your business quality. The route forward is an acquirer that holds the registrations your category requires. At CARDZ3N we are a Las Vegas-based high-risk merchant account provider backed by top-tier sponsor banks. Our underwriting support is hands-on, and our multi-bank approach is built to give approvals resilience if one route tightens.
If you want a quote, start with our high-risk merchant account page. Subscription and recurring billing models can go straight to high-risk subscription merchant accounts, and our online payment processing page covers card-absent selling. Pricing is quote-based, and reserve terms are explained as part of that quote.
Our view on high-risk MCCs
Merchants often treat the code as a stain. We treat it as a routing instruction. Visa’s own program requires acquirers to be registered per category, so the question is never whether your business is acceptable. It is whether the acquirer in front of you is built to carry it.
That is why we are a specialist and not a generalist. Our approach is hands-on underwriting, multiple sponsor banks and rails so approval does not hinge on one relationship, and plain terms on reserves and quote-based pricing. A merchant who knows their code, their category rules and their dispute ratio walks into underwriting as a prepared applicant, and that is the merchant we want to board.
The strongest accounts we see in principle are the ones where the business description, the MCC and the real transaction mix all agree.
Joshua Benedetti
Yes, for card-absent crypto activity. Visa’s manual lists 6051 (with 6012) as high integrity risk for exchanges, wallet providers and on-ramp providers, with transactions required to use Special Condition Code 7. Businesses in this category need an acquirer that is registered to carry it.
It is a registration category. 7994 (Video Game Arcades/Establishments) is the category Mastercard uses for skill games, so operators of skill-based games should expect registration requirements and fuller underwriting. A plain in-person arcade is a different profile from an online skill-game operator, so describe your model precisely.
MCC 5967 is Adult Content and Services, covering subscriptions, video streaming, audio-text and, in Visa’s October 2026 manual, escort services. Visa places it on its all-card-absent high-integrity-risk list, and Mastercard directs audiotext and videotext providers such as adult chat sites to use it.
MCC 7273 is Dating Services. It is on Visa’s high-integrity-risk list for card-absent transactions. Escort services moved from 7273 to 5967 in Visa’s October 2026 manual edition, so confirm your code if you were classified under 7273 before.
No. Your acquirer assigns it from your business description, and the card network can require corrections. If your business has genuinely changed, ask your acquirer for a review and document the new revenue mix.
Every merchant's processing setup is different, so the right answer depends on your industry, sales channels, average ticket size and chargeback history. CARDZ3N's payments specialists review those details with you and match your business with the right sponsor bank, gateway and risk tools, whether you sell online, in store, by invoice or on a recurring subscription.
We work with merchants across the USA, Canada, the UK and the EU, including high-risk, B2B and fast-growing businesses that traditional processors often turn away. If you would like a second opinion on your current rates, contract terms or approval options, contact our team for a free, no-obligation processing review.
Joshua Benedetti is the CEO of CARDZ3N, a Las Vegas-based merchant services provider specializing in high-risk payment processing and B2B payment technology.
Joshua Benedetti on LinkedInCARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.