 CARDZ3N — Home
Contact us today for personalized advice and strategic solutions tailored to your goals.

Call us
+1 (702)-623-3528


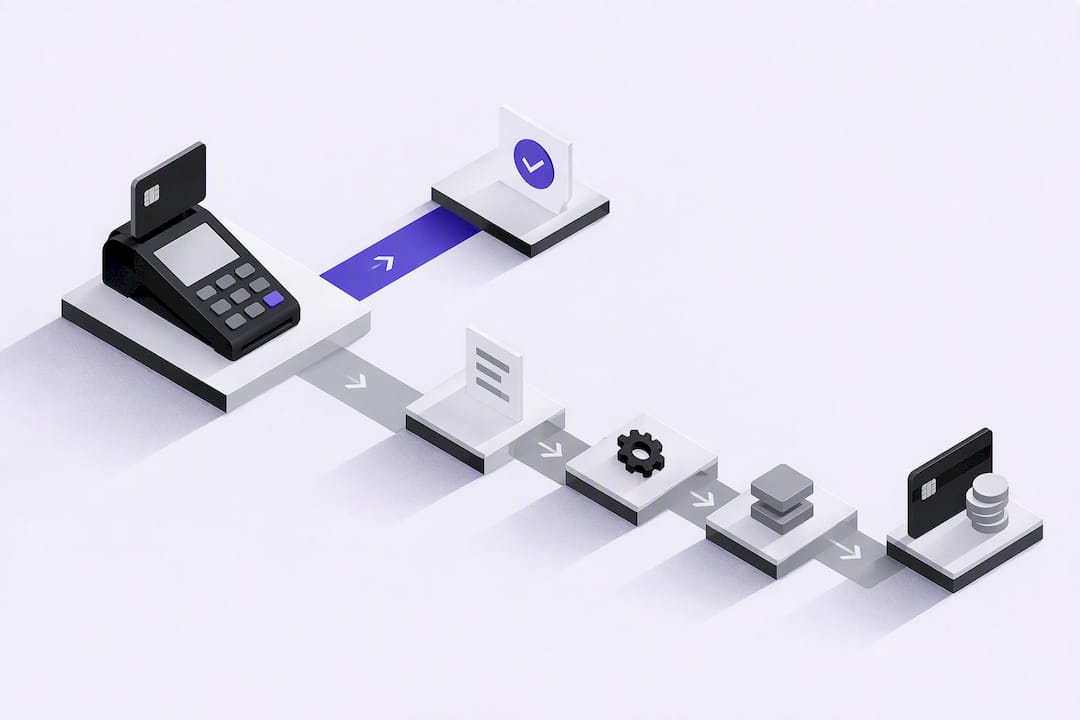
Collection agencies and debt buyers collect payments from people who may dispute the debt, the amount or the charge itself. That is why a debt collection merchant account is classed as high risk and why many standard processors decline the category.
Disputes, regulatory scrutiny and reputational concerns all weigh on banks. Collection activity is governed by federal rules such as the Fair Debt Collection Practices Act and by state licensing, so acquirers want proof that you operate within them.
Many agencies offer both cards and bank debits. ACH and eCheck payments can reduce cost and dispute exposure; see ACH processing and eCheck vs ACH. Payment plans need written authorization, stored securely through tokenization.
Document every authorization, send receipts, keep descriptors clear and respond to disputes with records. Tools from chargeback management help. Always confirm your practices with your own compliance counsel.
Learn about our debt collection payment solutions and high risk accounts, or talk to CARDZ3N about your agency.
Every merchant's processing setup is different, so the right answer depends on your industry, sales channels, average ticket size and chargeback history. CARDZ3N's payments specialists review those details with you and match your business with the right sponsor bank, gateway and risk tools, whether you sell online, in store, by invoice or on a recurring subscription.
We work with merchants across the USA, Canada, the UK and the EU, including high-risk, B2B and fast-growing businesses that traditional processors often turn away. If you would like a second opinion on your current rates, contract terms or approval options, contact our team for a free, no-obligation processing review.
Joshua Benedetti is the CEO of CARDZ3N, a Las Vegas-based merchant services provider specializing in high-risk payment processing and B2B payment technology.
Joshua Benedetti on LinkedInCARDZ3N Inc is headquartered in Las Vegas, Nevada, and provides merchant services to businesses that traditional processors turn away. Backed by top-tier sponsor banks and processors, CARDZ3N combines institutional stability with the speed of a specialized team that understands high-risk industries. Services include high-risk account underwriting and placement, gateway solutions across the major gateway platforms, POS integrations, ACH and check processing, chargeback prevention through ChargebackZ3N, and business lending and working capital. Its AerospacePay division serves OEMs, MROs, FBOs, and repair stations with B2B and B2G payment processing. CARDZ3N serves merchants in the USA, Canada, the UK, and the EU.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.