



If you take payments by phone or mail, or you've spotted an unfamiliar line item on your processing statement, two sets of terminology come up constantly: MOTO transaction processing and card decline codes. Neither is as confusing as it first looks once you know what each term is actually referring to.
MOTO stands for "mail order/telephone order." A MOTO transaction is any card payment where the cardholder isn't physically present and the card isn't swiped, dipped, or tapped — the merchant instead keys in the card number manually after receiving it by phone or through a mail-in order form. Because the card is never physically presented, MOTO transactions carry more fraud risk than card-present sales, which is why they're priced and underwritten differently from retail swipe transactions.
Common MOTO use cases include call-center order taking, subscription services collecting a card number over the phone, and any business that still accepts mail-in payment forms. A MOTO-capable merchant account and virtual terminal let staff key in a card number, expiration date, and CVV manually, with additional fraud tools — like address verification (AVS) and manual review thresholds — layered in to offset the higher risk.
"MTOT DISC" (or "Bankcard MTOT Disc") is simply an abbreviation processors use on a merchant statement for the discount rate applied to MOTO transactions — the percentage fee charged on mail order/telephone order sales specifically, as opposed to the (usually lower) discount rate applied to card-present, swiped transactions. Seeing this line item just means some portion of your processing volume that period came through as a keyed, card-not-present MOTO sale rather than a physical card swipe or tap.
When a transaction doesn't go through, the response includes a decline code that tells the merchant (and, eventually, the customer) roughly why. A few of the most common:
None of these codes mean the merchant did anything wrong — they originate from the cardholder's issuing bank, not the processor. But a business seeing a pattern of 05s, 57s, or 59s on MOTO or card-not-present volume is a signal worth reviewing with a processor who actually underwrites for that risk profile, rather than one built primarily around card-present retail.
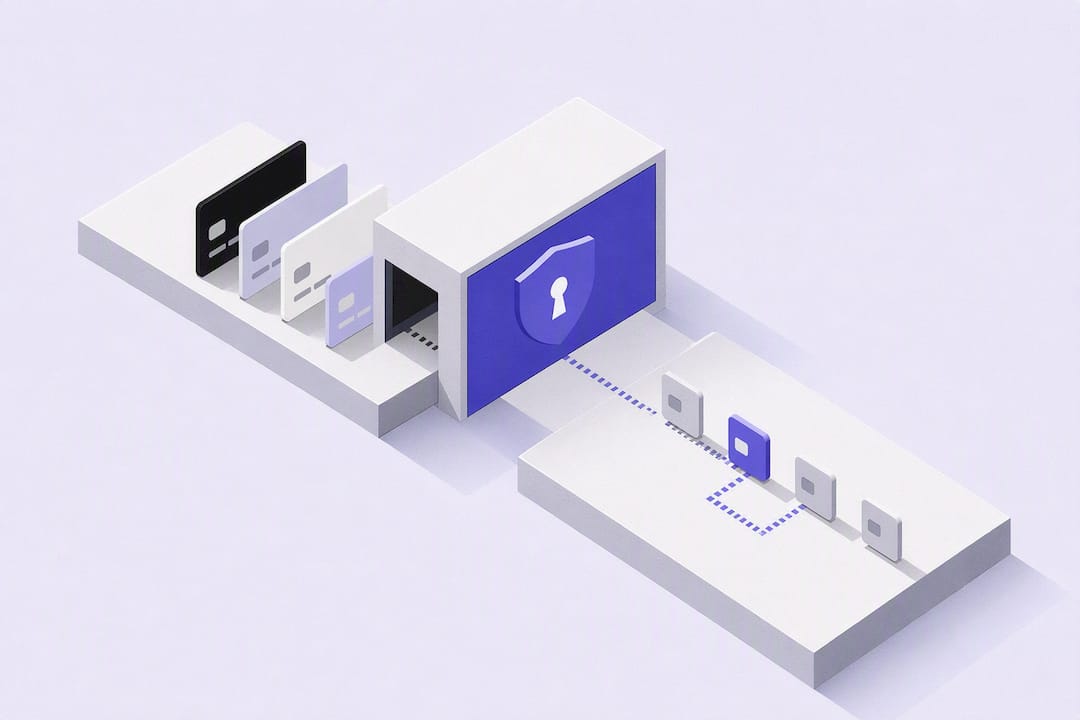
Any business taking recurring or repeat MOTO payments eventually asks about storing credit card information for future use. Done correctly, this means tokenization — the actual card number is replaced with a randomized token on the merchant's side, and the real number is stored only within a PCI-compliant vault, never on the merchant's own systems. This is what makes recurring billing, card-on-file, and repeat phone orders possible without re-keying a card number (and re-exposing PCI scope) every time.
CARDZ3N underwrites MOTO and card-not-present merchants directly, with fraud tools tuned for keyed transactions (AVS, CVV matching, velocity checks) and tokenized card storage for recurring billing — rather than treating MOTO as an afterthought bolted onto a card-present retail account.
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.