






In the fast-paced world of business transactions, understanding B2B payments is crucial. As businesses work to optimize operations and improve financial efficiency, the details of these transactions matter more than ever.
Imagine a world where your business payments are seamless, fast, and secure. That isn't just wishful thinking — it's an achievable reality with the right approach to B2B payments. By exploring the differences between B2B and consumer payments, you can unlock strategies that improve your business's financial operations.
How do these differences affect your business, and why do they matter to you?
Payment processing is the backbone of financial transactions in business. Efficient B2B payment processing keeps operations running smoothly and cash flow healthy. But what sets B2B payments apart from consumer payments, and why should businesses care?
Business owners know that effective B2B payment processing is essential for healthy cash flow. Unlike consumer transactions, which are often simple, B2B payments can be complex. They involve higher volumes and more detailed invoicing. Streamlined B2B payment solutions can cut processing times and boost efficiency. When a business processes payments quickly, it maintains liquidity and avoids cash crunches.
The right payment gateway can have a major impact on a business's financial outcomes. By choosing the right B2B payment gateway, businesses can ensure secure transactions, reduce fees, and improve payment execution. This isn't just about moving funds — it's about doing so in a way that protects the business's financial interests.
B2B payment processing often involves more complex invoicing than consumer payments. This complexity requires strong accounting and ERP systems to handle payment automation, invoice capture, and reconciliation. When these systems are integrated properly, they streamline processes and strengthen relationships with suppliers and clients.
ACH payments and electronic bank transfers also play a key role in B2B transactions. These methods enable secure, efficient payment execution while reducing manual work and errors. For decision-makers, that means more time for strategic work instead of routine payment tasks.
What separates B2B payments from consumer payments? The differences go beyond transaction size — they also involve different levels of complexity, risk, and control. Understanding these differences is key to optimizing your B2B payment processing strategy.
Business transactions generally involve larger amounts and require more secure payment methods than consumer payments. When a company pays a supplier, the stakes are higher: a single missed or incorrect payment can disrupt supply chains or damage important relationships. Security controls and approval workflows must be strong to prevent fraud and make sure funds transfer correctly and on time.
B2B payments often come with extended payment terms and more detailed invoicing. While a consumer might pay at checkout or through an automatic subscription, businesses frequently operate on net-30, net-45, or net-60 terms.
This delay requires careful planning and B2B cash flow management to make sure obligations are met without straining resources. Businesses must balance when they pay suppliers against when they receive payments from customers.
The approval process is another key difference. Consumer payments are typically completed in a single step, but B2B payments often require multiple stages of approval. A standard B2B workflow might include:
This structured approach helps transactions meet standards for authorization and compliance, which is vital for financial integrity and internal controls.
Tax and regulatory requirements further separate B2B from consumer payments. B2B transactions often need to account for sales tax, VAT, use tax, and industry-specific regulations. Cross-border B2B payments may also involve additional rules around sanctions, anti-money laundering, and reporting. Financial managers need to understand these requirements to avoid penalties, stay compliant, and protect the organization from regulatory risk.
There are also technical differences between payment platforms built for businesses versus consumers. A B2B payment gateway usually supports multiple payment methods — such as B2B credit cards, B2B ACH payments, wires, real-time payments, and virtual cards — along with features like payment terms, invoice matching, and bulk payments.
Consumer payment gateways, on the other hand, are built for quick, one-time card or wallet transactions with little need for complex invoicing or approval processes. Choosing a solution built for B2B needs ensures your payment infrastructure can handle current demands and scale as your business grows.
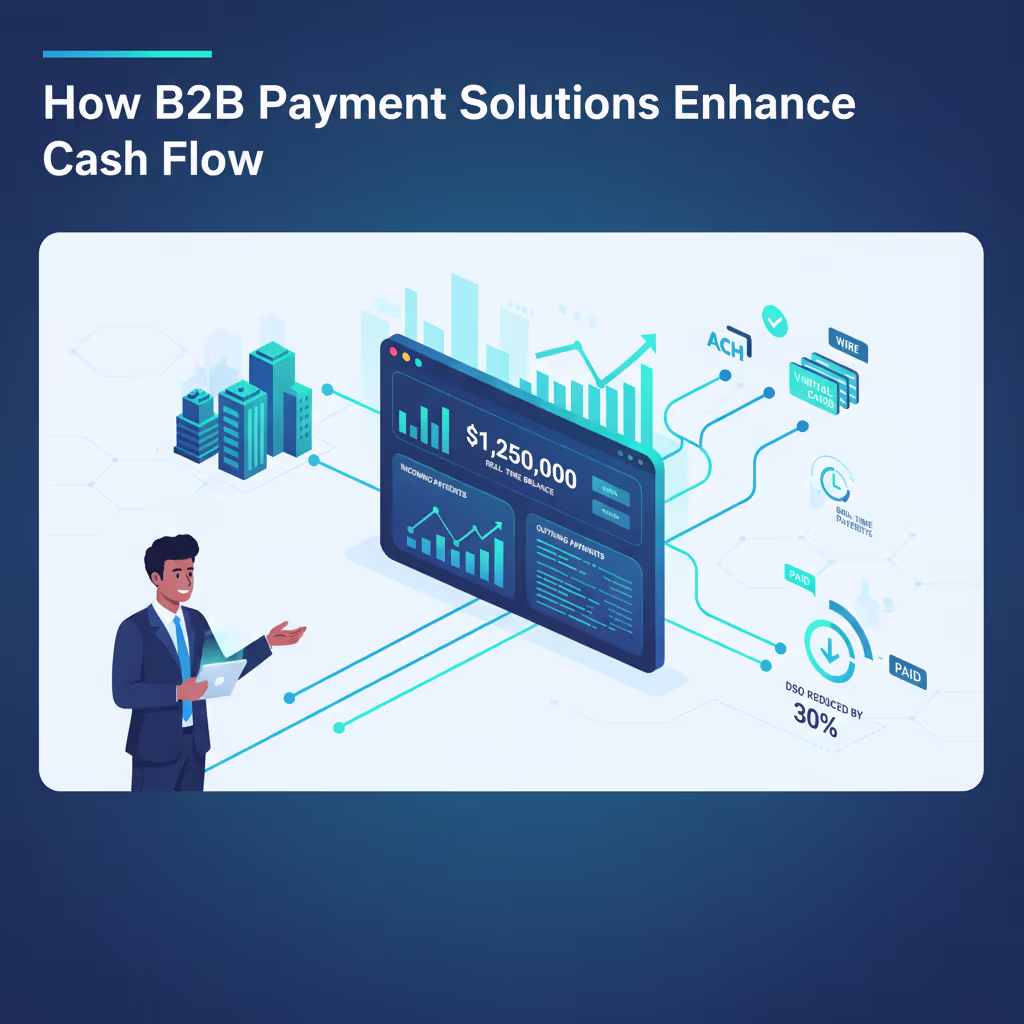
Cash flow is the lifeblood of any organization, and well-designed B2B payment solutions can significantly improve it. By optimizing how money flows in and out of the business, companies can see quick improvements in liquidity, forecasting, and financial resilience.
Companies that use advanced B2B payment solutions often see improved B2B cash flow through faster transaction processing and better visibility. When payments process efficiently, funds are available sooner — letting businesses reinvest in operations, pay down debt, or act on strategic opportunities. Speeding up collections and managing disbursements more intelligently can be a game-changer for working capital.
Automation plays a central role here. Businesses can cut administrative costs by automating B2B payment processing and invoicing. Automation reduces manual data entry and errors, freeing up time for finance and accounting teams to focus on strategic work instead. That reduction in overhead directly improves the bottom line.
For financial managers, accurate payment tracking and reporting make it easier to forecast cash flow. With clear insight into when and how payments happen, managers can see upcoming inflows and outflows, adjust spending, and avoid surprises. This visibility supports more confident decisions about hiring, investment, inventory purchases, and strategic projects.
Integrating B2B payment solutions with core accounting systems, ERP platforms, and treasury tools also streamlines financial operations. When payment systems are fully integrated, tasks like invoice capture, cash application, and payment reconciliation become simpler. This reduces the burden on accounting teams and improves data accuracy across the organization.
Businesses that adopt effective B2B payment strategies — supported by a capable B2B payment gateway and B2B merchant services — often end up in stronger financial positions with greater operational efficiency.
They're better equipped to accept payments from a wide range of customers, support international and cross-border payments, and manage risk. Over time, these capabilities help pave the way for sustainable growth and stability in a competitive market.
One of the most common tools in B2B merchant services is the B2B credit card. B2B credit card payments are especially useful when speed, convenience, and rewards matter. They can help businesses quickly pay suppliers, cover recurring software subscriptions, or manage expenses for distributed teams — all while earning points or cash back.
Credit card payments in a B2B context often settle faster than checks and may offer more predictable timing than other methods. That speed can improve B2B cash flow by reducing uncertainty around when funds arrive. For suppliers, accepting B2B credit cards can shorten days sales outstanding (DSO), limit collection risk, and give card-preferring customers a better experience.
However, B2B credit card fees are typically higher than bank-based methods like ACH. Interchange and processing fees are usually charged as a percentage of the transaction, sometimes with added per-transaction charges.
Specialized B2B merchant services and level 2/3 data can reduce these costs, but credit card acceptance still tends to be one of the more expensive payment options.
That's why many businesses reserve B2B credit cards for transactions where the benefits — faster payment, rewards, or customer preference — justify the added expense.
B2B ACH payments are another core component of modern B2B payment processing. ACH (Automated Clearing House) transfers move funds directly between bank accounts, making them well suited for recurring payments, subscription billing, payroll, and regular supplier invoices.
One of the biggest advantages of B2B ACH payments is cost. ACH fees are typically much lower than credit card processing fees, often charged as a flat per-transaction amount rather than a percentage of the total.
This makes ACH ideal for high-value invoices and ongoing relationships where controlling costs is a priority. Over time, shifting a portion of your B2B payment volume from cards to ACH can meaningfully reduce payment-related expenses.
ACH transfers also offer better predictability and control than paper checks. Payments can be scheduled, tracked, and reconciled more easily through a B2B payment gateway or integrated treasury platform.
This predictability improves B2B cash flow planning, helping both payers and payees manage their bank balances more effectively. For many finance teams, ACH becomes the default "workhorse" method for domestic B2B payments.
Both B2B credit cards and B2B ACH payments play important roles in a modern payment mix, but they differ sharply in how fees are structured and how they affect your bottom line.
B2B credit card transactions typically involve percentage-based interchange fees plus processing costs. Each payment may incur a fee of a few percentage points of the transaction amount, along with fixed per-transaction charges. For large B2B invoices, these percentage-based fees can add up quickly.
Businesses that rely heavily on card payments may see higher overall payment costs, even with benefits like rewards, chargeback protection, or improved customer satisfaction.
In contrast, B2B ACH payments usually carry much lower, mostly flat fees. Instead of paying a percentage of the transaction, businesses often pay a small, fixed fee for each ACH transfer.
This makes ACH especially attractive for high-dollar B2B payments, where even a small percentage fee on a large invoice can add up. By routing larger payments to ACH while using B2B credit cards for smaller or time-sensitive transactions, companies can optimize both cost and convenience.
The right strategy is rarely all-or-nothing. A balanced approach — supported by a capable B2B payment gateway and thoughtful B2B merchant services — lets businesses offer multiple payment options while guiding customers toward the methods that best support cash flow and margin goals.
Over time, this mix can improve profitability, strengthen relationships, and create a smoother payment experience for everyone involved.
Understanding and optimizing B2B payments can have a major impact on your business's financial health. From maintaining strong B2B cash flow to navigating complex regulatory and compliance requirements, the right combination of B2B payment processing, merchant services, and gateways offers clear advantages.
B2B payments differ from consumer payments in transaction volume, complexity, risk, and regulatory requirements. By choosing effective B2B payment gateways, using tools like B2B credit cards and B2B ACH payments, and integrating systems across accounting and ERP platforms, businesses can improve efficiency, reduce costs, and gain stronger control over cash flow.
As you evaluate your own payment strategy, consider which mix of methods and technologies will best support your growth and resilience. The more intentional you are about B2B payment processing today, the better positioned your business will be to adapt, compete, and thrive in the years ahead.
B2B payments refer to transactions between two businesses. Unlike consumer payments, these transactions often involve larger sums and may require additional services like invoicing, purchase orders, and extended payment terms.
B2B payments can be conducted through various methods such as wire transfers, checks, ACH payments, or specialized payment gateways. Efficient B2B payment processes are crucial for maintaining healthy cash flow and solid business relationships.
A B2B payment gateway is a technology solution that facilitates electronic transactions between businesses. Unlike consumer payment gateways, B2B gateways handle larger volumes and more complex processes, such as invoicing and bulk payments. It supports methods like B2B credit cards, B2B ACH payments, wires, and virtual cards, while handling encryption, authorization, and settlement behind the scenes.
These gateways are designed to accommodate the specific needs of businesses, including multi-currency support and customized reporting. They ensure secure, efficient, and reliable transactions, making them essential for modern businesses engaged in regular trade with other companies.
Yes, many modern payment platforms are built to support both B2B payments and consumer (B2C) payments on the same underlying infrastructure.
In practice, they offer additional features for B2B use cases — such as invoicing, customized payment terms, higher transaction limits, and integrations with ERP or accounting systems — while still allowing you to accept consumer-style card or digital wallet payments when needed.
This flexibility helps businesses manage all their payment flows through a unified B2B merchant services stack.
Many digital wallets and online payment platforms can be used for B2B payment processing, especially for smaller invoices, services, or cross-border transactions. Businesses may use these tools to send invoices, accept online payments, or manage subscriptions, often alongside more traditional methods like ACH and wires.
However, for larger, recurring B2B transactions, companies generally rely more on B2B ACH payments, wires, and card-based solutions integrated into a dedicated B2B payment gateway for better control, lower fees, and stronger back-office integration.
By choosing CARDZ3N, you can focus on what matters most - growing your business, while they handle your payment processing needs. (702) 623-3528, 4262 Blue Diamond Rd Bldg 102 Ste 191 Las Vegas, NV 89139
Start protecting your revenue from chargebacks today — schedule your complimentary consultation with CARDZ3N’s dispute management specialists.